How to protect yourself from high-pressure solar deals, caregiver mistreatment, financial exploitation, and other forms of abuse.
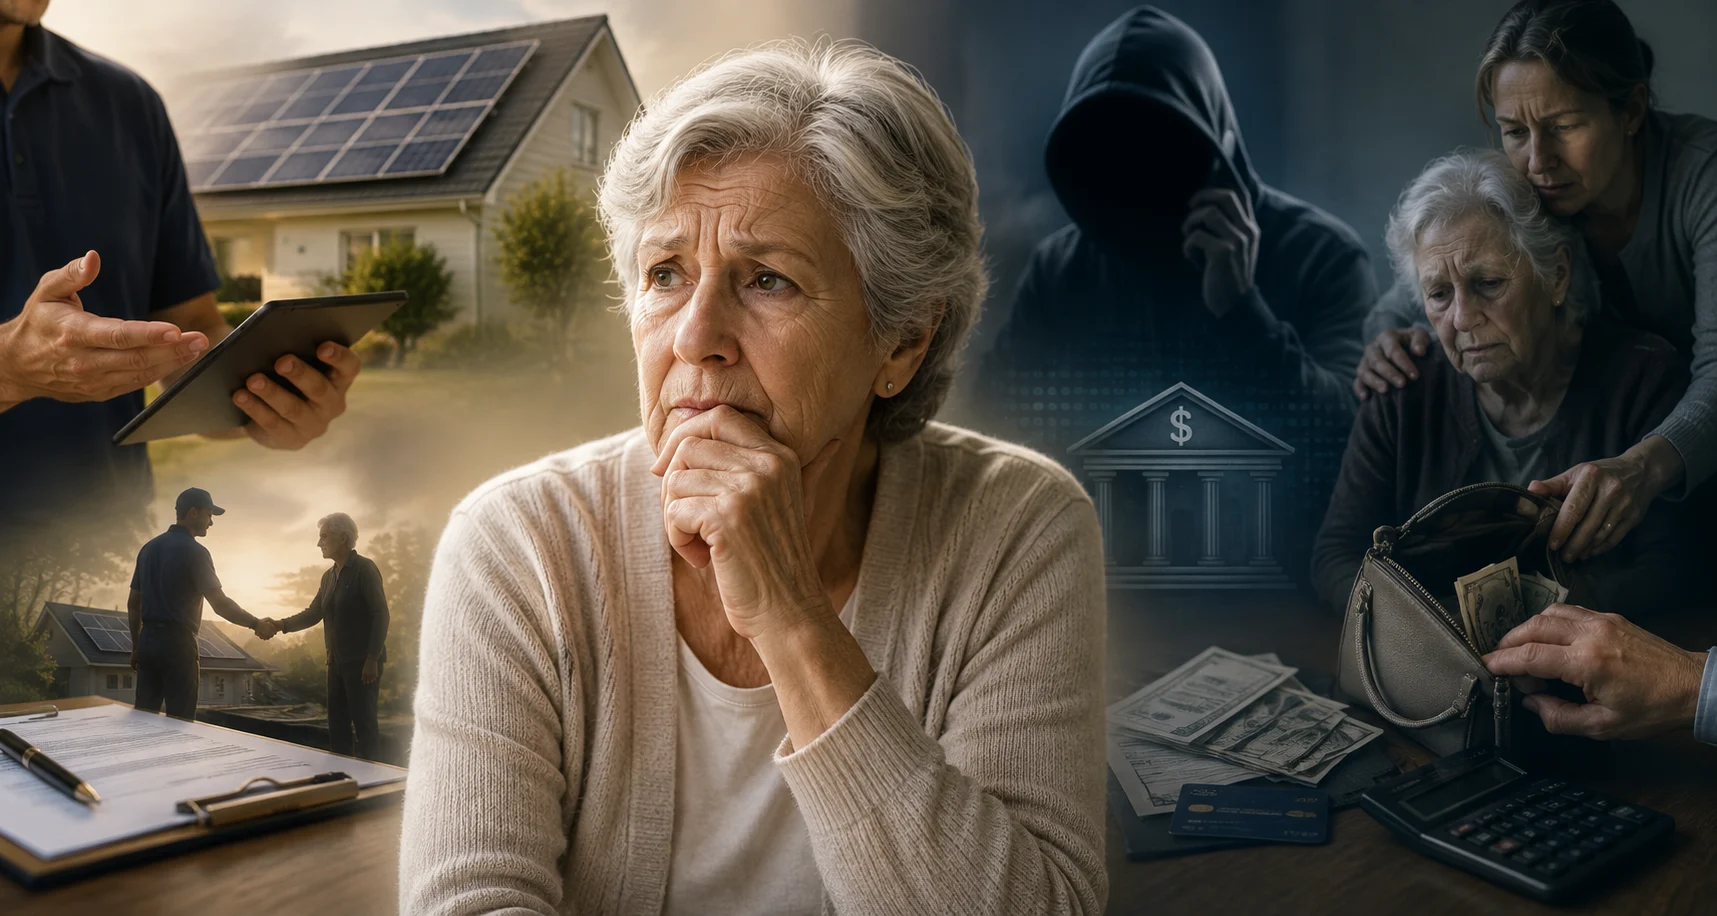
Abuse does not always arrive as a visible injury or an obvious crime. It may begin with a high-pressure solar pitch at your door, a relative “borrowing” money and not repaying it, a caregiver controlling your telephone, or a professional charging you for work that was never completed. The paperwork may look legitimate, and the person may be familiar, trusted, or persuasive. But if you are being pressured, isolated, misled, neglected, or denied control over your own choices, the harm is real.
“Not fraud, but abuse” describes conduct that may not look like a classic scam but still takes away your safety, money, dignity, or independence. Financial exploitation can involve someone misusing your money or property through pressure, manipulation, harassment, or betrayal of trust. Emotional abuse, neglect, and isolation can happen at the same time. Growing older does not make you incapable, and needing help does not give anyone the right to control or exploit you.
Solar Sales: One Example of a Larger Problem
Residential solar can reduce energy costs for many households, and reputable installers provide real value. The concern is the sales and financing system surrounding some transactions. Federal regulators have warned about hidden loan markups, exaggerated savings, misleading descriptions of tax credits, and monthly payments that rise unless the borrower makes a large prepayment. The Consumer Financial Protection Bureau reported that certain financing fees can increase a solar loan’s principal by 30 percent or more above the cash price.
The federal solar tax credit is another source of confusion. It is a credit against eligible federal tax liability—not a guaranteed cash rebate for every buyer. A retiree with limited tax liability may not receive the benefit in the way a salesperson’s “net price” illustration suggests. If a loan assumes that the customer will apply an amount equal to the credit toward the balance, the monthly payment may later increase when that payment is not made.
The Tactics That Cross the Line
- Manufactured urgency: “This offer expires today,” “Your neighborhood has only two spots left,” or “You must sign now to qualify.”
- False authority: Implying affiliation with a utility, government agency, homeowners association, or official energy program.
- The “free solar” claim: Describing a financed purchase, lease, or power-purchase agreement as free or no-cost.
- Tablet signing without meaningful review: Asking the homeowner to tap initials or sign while the representative controls the screen, scrolls quickly, or minimizes disclosures.
- Hiding the cash price: Focusing only on a monthly payment while omitting loan principal, financing fees, interest, term, and total cost.
- Overpromising savings: Treating estimates as guarantees without accounting for shade, roof condition, utility-rate changes, household use, system downtime, or maintenance.
- Isolation: Discouraging the customer from calling an adult child, trusted adviser, tax professional, or competing installer.
- Persistence after refusal: Repeated calls, texts, or visits that wear down resistance rather than earn informed consent.
Other Abuse That Can Look Like Ordinary Business or Family Life
Contractor and home-repair exploitation. A roofer, handyman, alarm company, or remodeling business may demand a large upfront payment, create unnecessary work, place an improper lien, or leave a project unfinished. The transaction may begin as a real service agreement but become abusive when pressure, inflated charges, or deliberate confusion replace informed consent.
Misuse by relatives, caregivers, or trusted agents. Warning signs include unexplained withdrawals, unauthorized card use, unpaid household bills despite adequate income, sudden account changes, a new joint owner, altered estate documents, or misuse of a power of attorney. Financial abuse is often committed by someone the older adult knows.
Professional and fiduciary abuse. A broker, adviser, lawyer, tax preparer, guardian, or other professional may recommend unsuitable products, move money for personal benefit, overbill, conceal conflicts, or pressure a client to grant control. A title or license does not eliminate the need for independent review.
Caregiver neglect and coercive control. Abuse may include withholding food, medication, hygiene, transportation, visitors, mail, or access to money. It can also involve threats, humiliation, intimidation, overmedication, or isolating a person from friends and family. These behaviors may leave no immediate financial paper trail, but they deserve urgent attention.
Imposter, investment, romance, and technology schemes. A stranger may pose as a government official, bank employee, technology-support worker, business representative, or online companion. The story changes, but the pattern is similar: unexpected contact, urgency or fear, secrecy, and instructions to move money in a specific way. No legitimate government agency will demand that someone transfer funds, buy gift cards, use a cryptocurrency ATM, or hand cash or gold to a courier to “protect” assets.
Four Doors Abuse Can Walk Through
The following scenes are anonymized composites based on documented patterns. The details are combined to protect privacy, but the pressure, isolation, and losses they portray are real.
“Just Tap Here, Mr. Harris”
At 78, Mr. Harris knew what his power bill cost. What he did not know was why a stranger wearing a utility-style badge was standing in his kitchen, turning a tablet toward him. “This is not a loan,” the salesman said. “It is a government-backed energy program. Just tap here so we can inspect the roof.” Mr. Harris asked to call his daughter. The salesman glanced at the clock. “If we leave without submitting it, you lose the discount.” Twenty minutes later, Mr. Harris had signed a 25-year financing agreement. The promised savings were estimates. The tax credit had been treated like guaranteed cash. Months later, his electric bill remained—and a new loan payment arrived beside it.
The warning: False authority, manufactured urgency, isolation, and a signature obtained without informed review can turn a legal-looking sale into exploitation.
“I’m Only Helping With the Bills”
After his wife died, 84-year-old Mr. Lee let a nephew move into the spare room. The nephew drove him to appointments, picked up groceries, and began “helping” with online banking. Soon, paper statements stopped arriving. When Mr. Lee asked about a missing pension deposit, the answer was always the same: “You forgot what you spent.” A niece later found cash withdrawals, a new credit card, and the nephew’s name added to an account. Nothing had been taken in one dramatic robbery. It disappeared in small transfers, late-night purchases, and the steady suggestion that Mr. Lee could no longer trust his own memory.
The warning: Control of mail, passwords, transportation, and information can be as powerful as control of the money itself.
The Room at the Top of the Stairs
Ms. Daniels, 76, moved in with family after walking became difficult. Her bedroom was upstairs. Food came when someone remembered; water sat beyond her reach. Visitors were told she was sleeping. On the telephone, a relative stood beside her and answered every question. At the hospital, staff noticed dehydration, poor hygiene, and missed medication. Ms. Daniels quietly insisted that everything was fine. Dependence had taught her the cost of complaining: “If I make trouble,” she whispered when finally alone, “where will I go?”
The warning: Neglect often hides behind privacy, family loyalty, or a rehearsed assurance that nothing is wrong.
“Your Money Is Under Attack”
The caller knew the bank’s name and the last four digits of the account. He said he worked with federal investigators and warned 81-year-old Mrs. Alvarez that criminals had compromised her savings. To “protect” the money, she had to keep the investigation secret, withdraw cash, and hand it to a courier using a case number. The caller stayed on the line as she dressed, drove to the bank, and answered the teller’s questions. When the courier left, so did decades of savings. The badge, the case number, and the emergency had all been theater—but her fear was real.
The warning: Government agencies and banks do not order people to move money, buy gift cards, use cryptocurrency machines, or give valuables to couriers for safekeeping.
Warning Signs You Should Not Ignore
One warning sign may have an innocent explanation. A pattern deserves attention—especially if you feel afraid, rushed, isolated, confused, or newly dependent on someone who controls your money, transportation, mail, telephone, or visitors. Trust your instincts. You do not need to wait until you can prove wrongdoing before asking for help.
- Money leaves your accounts without a clear explanation, or bills go unpaid even though funds are available.
- Someone adds a name to your bank account, deed, beneficiary form, or power of attorney without your full understanding.
- A caregiver or relative answers for you, blocks visitors, monitors calls, or refuses to leave you alone with a doctor or banker.
- You are missing medication, meals, hygiene care, transportation, or medical treatment you need.
- You have injuries you cannot comfortably explain, or you are afraid of someone responsible for your care.
- You are asked to sign a major contract that you cannot explain in your own words.
- You are told to buy gift cards, use a cryptocurrency machine, withdraw cash, or move money to “protect” it.
- A new friend, adviser, contractor, caregiver, or romantic interest demands secrecy or quick access to money.
- You paid for services that were not performed, were charged far more than expected, or notice property is missing.
- You find yourself thinking, “They will be angry if I tell,” “I have no choice,” or “I am not allowed to talk about it.”
How You Can Report Abuse or Exploitation
Start with your safety. If you are in immediate danger, call 911. If it is safe, move to a room, neighbor’s home, public place, medical office, or other location where you can speak privately. For concerns involving abuse, neglect, self-neglect, or financial exploitation, contact Adult Protective Services where you live. The Eldercare Locator can connect you with local help at 1-800-677-1116. You do not have to investigate the situation or prove a crime before asking for assistance.
- Adult Protective Services: Tell the local APS agency if you believe you are being abused, neglected, or financially exploited—or if you are worried about another older adult.
- Law enforcement: Call 911 for immediate danger. Otherwise, call your local police or sheriff’s non-emergency number about theft, forgery, assault, coercion, or misuse of your money.
- National Elder Fraud Hotline: Call 1-833-FRAUD-11 (1-833-372-8311), Monday through Friday, 10 a.m. to 6 p.m. Eastern Time, for help reporting suspected financial fraud.
- Federal Trade Commission: Report scams, deceptive sales, and impersonation at ReportFraud.ftc.gov.
- Consumer Financial Protection Bureau: Submit a complaint about a loan, lender, debt collector, mortgage, credit product, or financial service.
- State attorney general and licensing boards: Report deceptive contractors, solar sellers, home-repair businesses, insurance agents, financial professionals, or other licensed providers.
- Long-term care ombudsman: Report concerns about your care in a nursing home, assisted-living community, or residential care setting.
- Your bank or credit union: Ask for the fraud or elder-exploitation department. Request help protecting remaining funds, securing accounts, and determining whether a transfer can be recalled.
What to Gather When You Ask for Help
If it is safe, write down what happened, when it happened, who was involved, and whether you face an immediate risk. Keep contracts, account statements, canceled checks, messages, advertisements, photographs, and medical information. Store copies somewhere the suspected abuser cannot reach. Do not confront the person if doing so could put you in danger or cause your money or records to disappear. Even if you do not have every detail, make the call. You deserve to be heard.
Your Voice and Your Choices Still Matter
Asking for help does not mean surrendering your independence. Tell a trusted person what you want, ask to speak privately, and request explanations in plain language. You have the right to slow down a decision, seek a second opinion, refuse a visitor, review a contract, and ask questions about your own money and care. Age alone does not erase your rights. The goal of support should be your safety, informed choice, dignity, and control.
The Grey Fox Portal takeaway: If someone uses pressure, secrecy, fear, isolation, or trust to control your choices, take it seriously. Pause, speak with someone you trust, protect your records and money, and report reasonable concerns. You are not causing trouble—you are protecting yourself.
Take One Protective Step Today
Choose one action before you leave this page: save the reporting numbers in your phone, tell a trusted person about a concern, review a recent contract or bank statement, or create a firm rule that you will never sign a major agreement on the first visit. If something feels wrong, speak up today. If you are safe, help another older adult do the same. One conversation, one careful review, or one report can prevent a much greater loss—and remind every abuser that older adults are informed, connected, and not alone.
Editor’s note: This article provides general consumer information, not legal, tax, or financial advice. Rules, incentives, and cancellation rights vary by location and contract.

Leave a Reply
Your email is safe with us.